| |
 |
Tuesday, October 27, 2026 |
|
|
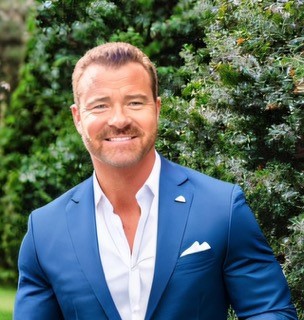
A Note From Tim Powers
🏡 The Holiday Market Advantage: Less Competition, More Opportunities to Close!
Happy Tuesday!
We're heading into the holiday season, and while some agents are beginning to slow down, this is exactly when opportunities can open up for those who stay active!
Buyers are still buying, sellers are still selling, and motivated clients want solutions—not reasons to wait.
Let's look at what's happening in the mortgage market and how we can turn it into more business!
📉 MORTGAGE MARKET UPDATE
Mortgage rates continue to be influenced by inflation expectations, economic data, and movements in the bond market.
The encouraging news is that buyers have more financing strategies available than simply accepting the first rate they're quoted.
Rates can change daily, and the right financing structure can make a meaningful difference in affordability.
National averages are for qualifying conventional mortgage scenarios and are not individual loan offers. Actual rates, APRs, and closing costs depend on credit, down payment, loan type, points, lender pricing, and market conditions.
My takeaway: The interest rate matters, but the entire financing strategy matters even more!
🏠 ARIZONA & WASHINGTON: THE HOLIDAY OPPORTUNITY
Phoenix / Scottsdale
As we enter the slower seasonal period, buyers may find opportunities with sellers who want their properties under contract before year-end.
For agents, this creates opportunities to negotiate closing-cost assistance, seller concessions, and potentially mortgage rate buydowns.
Washington State
The Washington market is also entering its typical seasonal slowdown.
With fewer buyers actively searching during the holidays, motivated purchasers may face less competition on certain properties.
The opportunity: Help your buyers recognize that less competition can sometimes mean better negotiating leverage.
Of course, conditions vary by neighborhood, price point, and property.
💰 3 WAYS TO MAKE MORE MONEY BEFORE YEAR-END
1️⃣ Target Listings That Have Been Sitting
Look for properties that have been on the market for 45–60 days or have experienced price reductions.
Instead of simply asking for another price reduction, consider negotiating seller-paid closing costs or an eligible temporary rate buydown.
Sometimes improving the buyer's initial monthly payment can be more appealing than a modest price reduction.
Send me a listing, and I'll help you compare the numbers!
2️⃣ Reconnect With Buyers Who Said, "We'll Wait Until Next Year"
This is a great time to revisit those conversations.
Try this:
"I know you were thinking about waiting until spring, but there may be some opportunities right now with less competition and motivated sellers. Would you be open to seeing what the numbers look like?"
You might be surprised how many buyers are willing to reconsider when they understand the opportunities.
3️⃣ Turn Your Open Houses Into Financing Conversations
Don't just collect names and phone numbers.
Offer buyers something valuable: a personalized payment comparison, down payment options, or an estimate showing how seller concessions could affect their upfront costs.
I'll gladly help you prepare financing scenarios for your listings and open houses.
The goal isn't just more leads. It's more qualified buyers ready to make offers!
⭐ ALREADY PREAPPROVED? SEND THEM TO ME ANYWAY!
Here's something I encourage every agent to remember:
A preapproval letter doesn't necessarily mean your buyer has the best financing available—or that every potential underwriting issue has been addressed.
With over 20 years of mortgage experience and access to 150+ lenders, I can review financing options that may not be available through the buyer's current lender.
A second opinion may uncover:
✅ More competitive interest rates or closing costs.
✅ Different financing structures that improve affordability.
✅ Additional purchasing power.
✅ Conventional, FHA, VA, jumbo, bank statement, DSCR, or other specialized financing options.
✅ Potential underwriting concerns before they jeopardize the closing.
Sometimes I'll find a better financing solution. Other times, I'll confirm that your buyer already has an excellent option.
Either way, you've added value to your client and taken another step toward protecting your transaction.
I'm not here to complicate your deals. I'm here to help you close more of them!
🚀 MY CHALLENGE FOR THIS WEEK
Before Friday, reach out to:
- 5 buyers who stopped looking earlier this year.
- 3 sellers who may be motivated to move before year-end.
- 2 buyers who are already preapproved with another lender.
That's 10 opportunities to create conversations and potentially generate your next commission!
And remember, if you have a buyer who needs a second opinion, has been declined elsewhere, or requires creative financing, I'm always happy to help.
Send me ONE buyer scenario this week—even if they're already preapproved. Let's see what we can accomplish together!
The agents who stay active through the holidays are the ones positioning themselves for a strong finish to 2026 and a great start to 2027.
Have a fantastic week!
Let's go sell some homes!
Tim Powers
|
Business Partner Update
DSCR loans: what your investor clients need to know
Rate Snapshot · November 16, 2026 |
▲ +0.22% |
|
Conventional 30-Year
7.26%
|
|
|
|
|
|
These are national mortgage index rates as of November 16, 2026. The 30-year fixed is at 7.26% — up 0.22% from last week, FHA at 7%, and VA at 6.88%. For exact rates tailored to your buyers, reach out to your loan officer directly.
Source: Optimal Blue daily mortgage indices via FRED
|
|
From Your Lending Partner
DSCR Loans Let Investors Buy on Cash Flow — Not Personal Income
|
|
Investor activity in this market remains strong, and the product fueling it is the DSCR loan — Debt Service Coverage Ratio. Unlike conventional investment property loans, DSCR doesn't look at the buyer's personal income at all. It qualifies based on the property's rent-to-mortgage ratio. If the home rents for $2,200 and the mortgage is $2,000, the DSCR is 1.1 — most lenders will approve at that level. This means a W-2 employee with a maxed-out debt ratio, a self-employed investor, or a foreign national can qualify based purely on the deal's cash flow numbers. There's no income documentation, no employment verification, no tax returns. Down payments are typically 20–25%, and rates run about 1–1.5% above conventional. I can close these in 21 days. If you're working with investors — or want to start — I can help you identify which of your listings would pencil as rentals and use that to attract qualified investor buyers. Let's talk.
I'll run DSCR numbers on any property in your portfolio — reach out today.
|
|
Mortgage News Daily
Residential construction failed to find even footing in September, with housing starts declining and single-family building permits pulling back, while total permits held nearly steady and completions edged higher. This week's Census Bureau data highlights weakness in new construction, particularly on the single-family side, while starts and completions were comparatively stable. Privately owned h
Read full article →
|
|
HousingWire
A town hall drew 1,000-plus attendees as members challenged the mandate and meeting restrictions
Read full article →
|
|
Mortgage News Daily
The National Association of Home Builders (NAHB)/Wells Fargo Housing Market Index (HMI) dropped three points to 29 in October--its lowest level in 14 years. As per usual, higher mortgage rates, rising costs, and worsening labor and lot conditions were the driving factors. All three component indices declined, with prospective buyer traffic suffering the steepest drop. HMI Component September
Read full article →
|
|
Did You Know?
Non-Warrantable Condo Financing
Get buyers into condos that conventional lenders reject.
Many condo buildings fail Fannie/Freddie warrantability tests — too many investor units, pending litigation, or HOA issues. Portfolio and non-QM lenders have programs for these buildings that your buyers are being turned away from.
|
✓Covers condotels, high investor-concentration buildings, and more
| |
✓Available from 10% down on some programs
| |
✓Rates slightly above conventional but often manageable
| |
✓I can evaluate any building's warrantability in 24 hours
|
|
|
Share With Your Buyers
Saving for a Home
|
|
1.
|
Your down payment doesn't have to be 20% — many loans allow 3–5% down.
|
|
2.
|
Don't forget closing costs — budget an additional 2–3% of the purchase price on top of your down payment.
|
|
3.
|
Gifted funds from family members are allowed on most loan programs — just document the transfer.
|
|
4.
|
Down payment assistance programs can cover your entire down payment if you qualify.
|
|
5.
|
Moving savings out of a checking account into a dedicated savings account makes it easier to document for your lender.
|
|
|
Tip of the Week
Test your sump pump before the rainy season by pouring water into the pit — a failed pump can lead to serious basement flooding.
|
|
|
16427 N Scottsdale Rd Ste 410, Scottsdale, AZ 85254 · +1 253-209-4247 · timpowersmortgage.com · NMLS# 178079 · Company NMLS# 181106
Book a meeting →
You are receiving this as a referral partner of Powers Group Financial powered by Barrett Financial Group LLC.
Unsubscribe
|
|